Our ‘Insights into MFRS 15’ series summarises the key areas of the Standard, highlighting some areas that are challenging to apply in practice, to assist reporting entities in understanding how to apply MFRS 15’s requirements.
MFRS 15 introduced the five-step model for revenue recognition and applies specifically to contracts with customers.
This article deals with Step 3 of the five-step model, which covers determining the transaction price. For a summary of the five-step model, refer to our article ‘Insights into MFRS 15 – Overview and scope’.
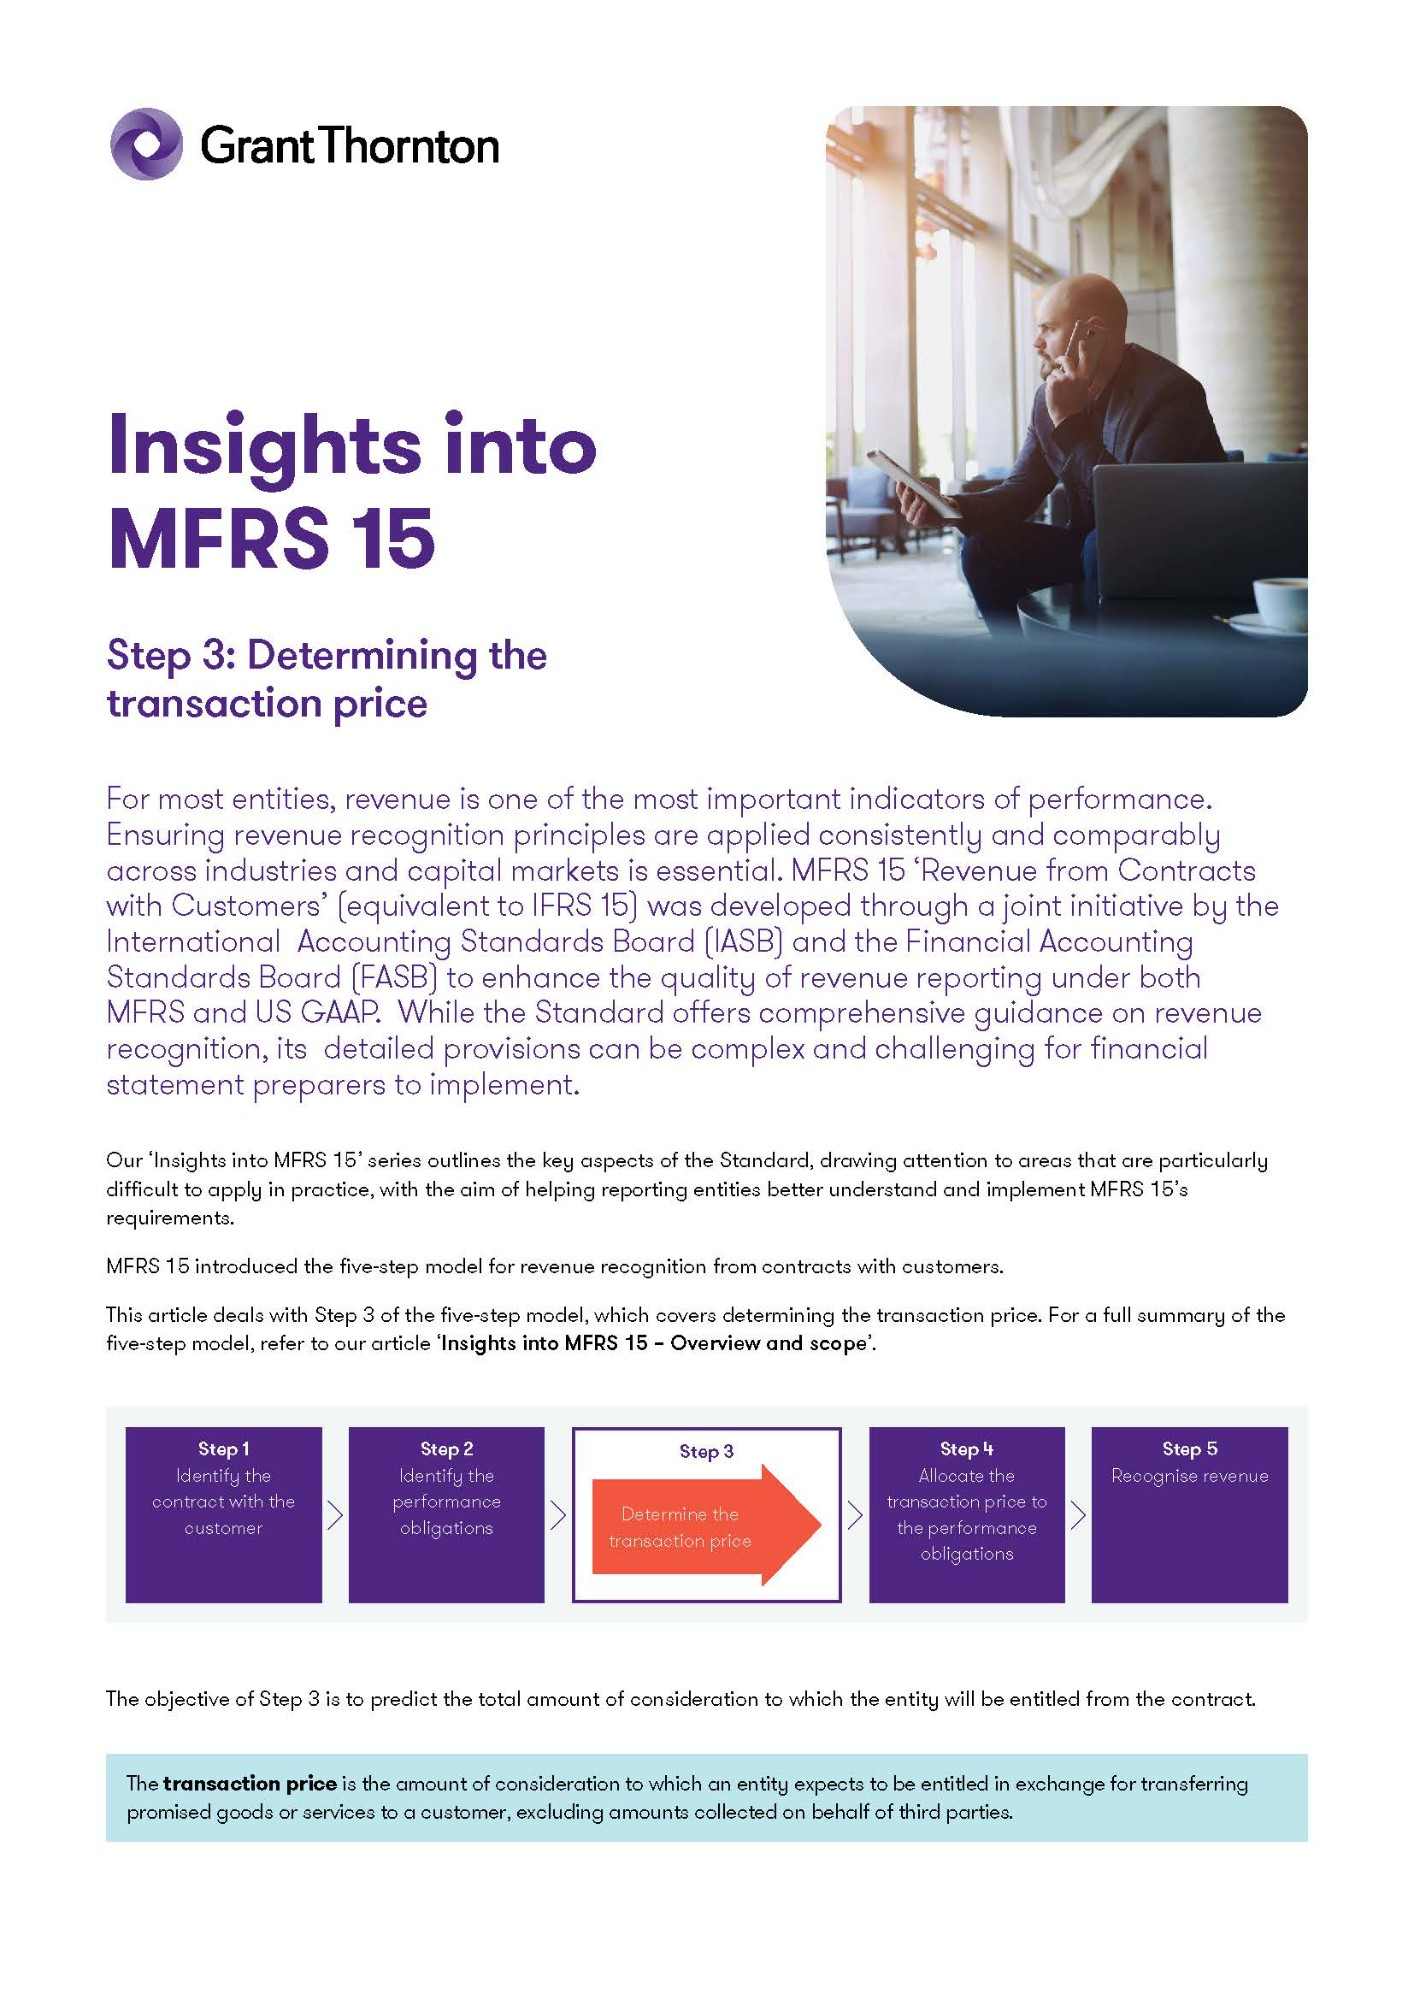
Step 3: Determining the transaction price
How we can help
We hope you find the information in this article helpful in giving you some insight into aspects of MFRS 15. If you would like to discuss any of the points raised, please speak to your usual Grant Thornton contact.